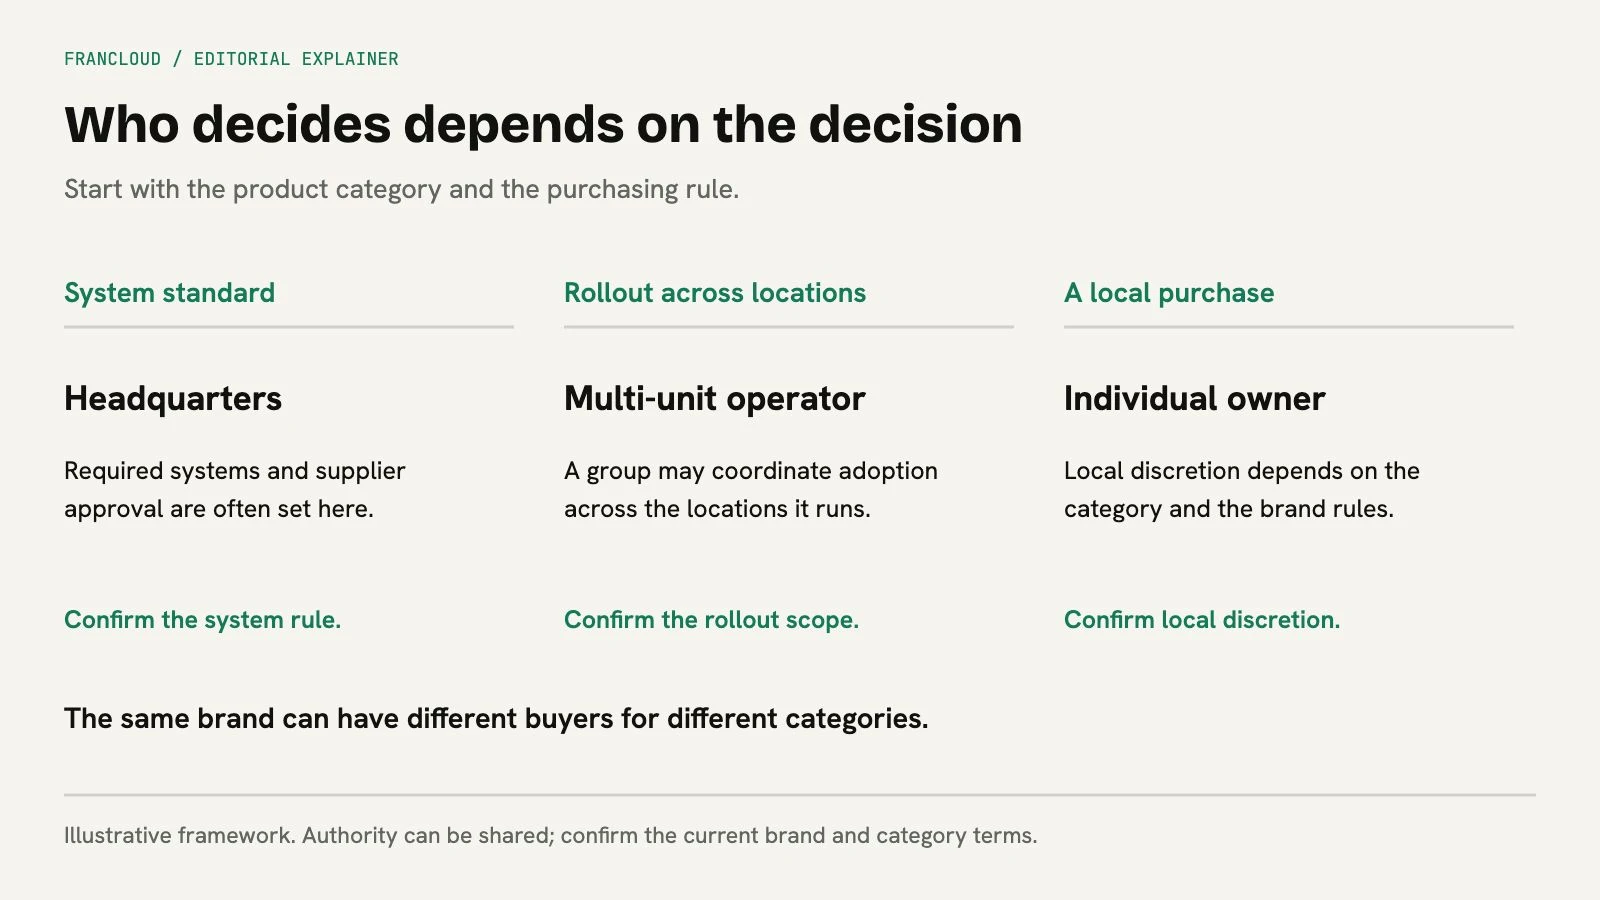
Selling to a franchise system is not one motion; it is three. Every franchise brand exposes three distinct doors to a seller: a corporate mandate negotiated with the franchisor, a rollout across the locations of a multi-unit operator, and a location-by-location ground game with individual franchisees. Each door has a different buyer, a different deal size, and a different sales cycle. Most teams pick one by habit, and the habit is expensive: sequences aimed at franchisees who cannot switch, quarters spent working HQ for a category it leaves to operators. The better move is to let the brand’s Franchise Disclosure Document tell you which door is actually open.
Why is selling to franchise systems different?
Franchise systems are different because ownership and authority are split: the franchisor owns the brand and the standards, while franchisees own the businesses that would actually pay you. A 500-location brand is not one account with 500 sites; it can be one HQ deal, or a few dozen operator deals, or hundreds of small ones, depending on how the franchisor writes its contracts. Treating a franchise brand like one enterprise account is a common reason pipelines stall.
The good news is that the split is documented. Under the FTC Franchise Rule, every franchisor selling in the US must publish an FDD and update it annually. The FDD spells out what franchisees must buy, from whom, and what discretion they keep. That means the org chart of the buying decision (the thing enterprise reps spend months mapping) is filed as a public document before your first call.
What are the three doors into a franchise account?
Door one: the corporate mandate
The corporate door means selling to the franchisor and becoming part of the required or approved stack. It is the biggest prize and the slowest cycle: one contract can cover every location, but the franchisor is deciding on behalf of hundreds of independent owners, so evaluation is cautious and political. This door wins when your category is one the franchisor already controls (point of sale, loyalty, brand marketing) and when consistency across locations is the franchisor’s stated priority. The signature on the contract is HQ’s, and the rollout clause lands in next year’s Item 11.
Door two: the multi-unit operator
The operator door means selling to a franchisee who owns several locations (sometimes dozens, sometimes across more than one brand). One relationship, many locations: an operator who signs can deploy your product at the locations they control without waiting for a system-wide decision, as long as the category is not locked down by the franchisor. Operators behave like mid-market buyers: they have a P&L, a head of ops, and real urgency about labor and margins. In mature systems, the ownership curve tends to be lopsided: a long tail of single-location owners and a short head of operators holding a meaningful share of the locations. The short head is where this door is. The FDD’s Item 20 exhibit is where those operators become visible, outlet by outlet; we cover how to read it in the Item 20 deep dive.
Door three: the single-unit ground game
The ground game means selling location by location to individual franchisees. Deal sizes are small and the motion is high-volume, so it only works when your product is self-serve or close to it. But the ground game has a strategic use the other doors lack: adoption inside a system is the strongest evidence you can bring to an HQ conversation. Ten locations running your product quietly is a pilot the franchisor didn’t have to fund. Teams who play this door well treat it as seeding, not as the end state: they instrument which locations adopt, collect the per-location results, and bring the numbers to HQ when the mandate conversation opens.
The three doors are not mutually exclusive; the strongest sellers into franchising run them in sequence. Ground-game locations prove the product, operators scale it inside a system, and the operator footprint becomes the case that wins the corporate mandate. What varies by brand is where the sequence can start, and that is exactly what the disclosure documents settle.
How does the FDD tell you which door is open?
The FDD tells you which door is open through its supplier and technology clauses. Item 11 discloses the computer systems and software franchisees are required to buy or use; Item 8 discloses which products and services must come from the franchisor or its designated suppliers. Read together, they sort every technology category in the system into one of three states: required, approved-supplier, or names no vendor, and each state points at a different door.
- Required system: the FDD names a required system in your category. The operator and single-unit doors are closed; your only real play is the HQ conversation.
- Approved-supplier list: franchisees choose among vendors the franchisor has vetted. Getting onto the list is an HQ conversation, but revenue then comes through operators and locations.
- Names no vendor: the FDD is silent or leaves the choice to the franchisee. Silent means unknown, not open, so confirm with an operator before you plan on the operator door.
This is the highest-value fifteen minutes in franchise prospecting: before building sequences or booking flights, check whether the door you plan to walk through exists. Brands that mandate a competitor are displacement accounts with a timing problem, not dead accounts; the who-uses-what hub shows which systems have disclosed which vendors, so you can sort your market into open doors and locked ones.
This is the pattern behind the three doors. A designated POS is the clearest hard mandate, one decision at head office, which is the motion most vendors plan for. Most other categories work differently. Where a brand runs an approved-supplier model: getting listed is necessary but sells nothing by itself, because every location still buys on its own. Those two models need different comp plans, different sales cycles and different definitions of a win, so reading which one you are facing before you build the forecast is worth more than any amount of pipeline discipline afterwards.
Who is on the franchise buying committee?
A franchise buying decision typically splits across three roles: HQ owns the rollout, the operator feels the pain, and finance signs. The franchisor’s ops or technology lead decides whether a tool becomes standard; they care about consistency, support burden, and how a rollout lands with hundreds of independent owners. The franchisee or operator is the daily user with the labor problem or the margin problem your product solves; they care about payback per location. And the check comes from whoever holds the P&L for the locations in question, which for an operator deal is the operator’s own finance lead, not the franchisor’s.
Pitches fail when they cross these wires: location-economics arguments aimed at HQ, brand-consistency arguments aimed at an operator. Match the message to the door. An HQ deck should read like a franchise-system operations case; an operator deck should read like a payback calculation on average unit volume.
One more wrinkle: in franchise systems the economic buyer and the beneficiary are often different companies. A franchisor can mandate a tool that franchisees pay for. Item 8 even requires disclosure of revenue the franchisor earns on required purchases. When HQ decides and locations pay, expect franchisee pushback to shape the evaluation. A seller who can show per-location payback is giving the HQ champion the internal ammunition they actually need.
What does the play look like end to end?
- Qualify the category. Check Items 8 and 11 in the brand’s FDD. Required, approved or names no vendor decides everything downstream.
- Pick the door. Category the filing leaves unnamed: confirm with an operator, then start there. Approved list: start the HQ listing conversation while selling to locations. Required competitor: log it and move on for now.
- Map the operators. Group the Item 20 directory by owning entity to find who controls multiple locations.
- Size the locations. Use Item 19 and AUV figures to confirm the locations can afford you at your price.
- Sell the door you picked: location-economics case to operators, system-consistency case to HQ.
- Convert adoption into the mandate. Once enough locations run your product, bring the results to the franchisor and move from vendor to standard.
How should you sequence a franchise account list?
Sequence by fit, not by size. The biggest brands attract every vendor’s first email and tend to have the most locked-down stacks; the best early accounts are usually mid-sized systems where the category is not locked, location economics support your price, and the system is growing. Three fit signals stand out in filings: the status of your category (unrestricted beats locked), the investment and fee structure in Item 7 and the royalty schedule (a franchisee already paying heavy fees has less discretionary budget), and outlet growth (a system opening locations is buying tools; a shrinking one is cutting them).
Doing this by hand means working through hundreds of pages per brand. Get my ranked accounts: FranDNA ranks the brands in the directory that fit what you sell and gives the reason for each. Paste your site and your work email and we send it.
What are the common failure modes?
- Pitching franchisees on a tool HQ mandates. The franchisee cannot switch even if they love your demo. Check the disclosed stack before the sequence goes out.
- Treating the brand as one account. A franchise system is a network of independent businesses under one flag. CRM hygiene that models operators as separate accounts pays for itself quickly.
- Deleting locked accounts. A required system today is a decision headquarters can change. Note the first year a mandate shows up, and watch what changes in the next filing.
- Skipping the seeding motion. Live locations make the HQ conversation easier. Ground-game adoption is evidence, and evidence wins mandates.
None of these are exotic mistakes; they are what happens when a horizontal playbook meets a franchised market. The fix is the same in every case: check the disclosure before the outreach. The FDD is the account brief; the playbook in how to read an FDD for franchise sales walks through the pre-call scan step by step.